Mortgages With Meaning

→ Voted Best Mortgage Broker in 2026

APPLY NOW

To help you streamline your finances, so you can live more freely, give more generously, and be present for the ones you love

Mortgage financing can be confusing, it doesn't have to be, here's the plan to making it simple.

Get started right away

The best place to start is to connect with us directly. The mortgage process is personal. Our commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let us cut through the noise, we'll outline the best mortgage products available, with your needs in mind.

Let us handle the details

When it comes time to arranging your mortgage, we have the experience to bring it together. We'll make sure you know exactly where you stand at all times. No surprises. We've got you covered.
Kambi Heywood

Hi, I’m Kambi, with over 27 years of experience in residential and commercial lending.


I work for you — not the bank — to find the best mortgage options for your unique situation, usually with no fees charged to you.


I’m proud to be part of BrokerSquared Paragon Mortgage Group, under the Tango network, and lead The Mortgage Central Team here in Cranbrook. This partnership gives me access to a wide range of trusted lenders and mortgage products, so you always get competitive rates and tailored solutions.


I’m also an active member of the community and a Charter Member of the Cranbrook Sunrise Rotary Club. Outside of work, I love life in the Canadian Rockies with my husband and children — and when I’m not helping clients, you’ll probably find me snowboarding, attempting to do yoga or run up a good hill somewhere.

Voted Best Mortgage Broker in 2026

Nice things people have said about working with me.
Kambi Heywood

Hi, I’m Kambi, an Accredited Mortgage Professional (AMP) with over 20 years of experience in residential and commercial lending. I’m dual-licensed in both BC and Alberta, which means I can help you with financing on either side of the Rockies.


I work for you — not the bank — to find the best mortgage options for your unique situation, usually with no fees charged to you.


I’m proud to be part of BrokerSquared Paragon Mortgage Group, under the Tango network, and lead The Mortgage Central Team here in Cranbrook. This partnership gives me access to a wide range of trusted lenders and mortgage products, so you always get competitive rates and tailored solutions.


I’m also an active member of the community and a Charter Member of the Cranbrook Sunrise Rotary Club. Outside of work, I love life in the Canadian Rockies with my husband and children — and when I’m not helping clients, you’ll probably find me snowboarding, practicing hot yoga, or diving into my next investment project.


LET’S TALK! 250-421-0540
CONTACT ME ANYTIME

Looking for some quick numbers?

Try THE AFFORDABILITY CALCULATOR

Start by telling us where you're at in your home buying journey.
Find out what you can afford in 30 seconds >

Find out if you can afford it in 30 seconds >

Find out how much you can take out in 30 seconds >

LEARN MORE ABOUT REVERSE MORTGAGES 

and other Mortgage Options for Seniors 55+.

LEARN MORE

Join the Best Years Club and learn how to live retirement life to its fullest!

Articles to keep you learning
By Kambi Heywood • November 12, 2026
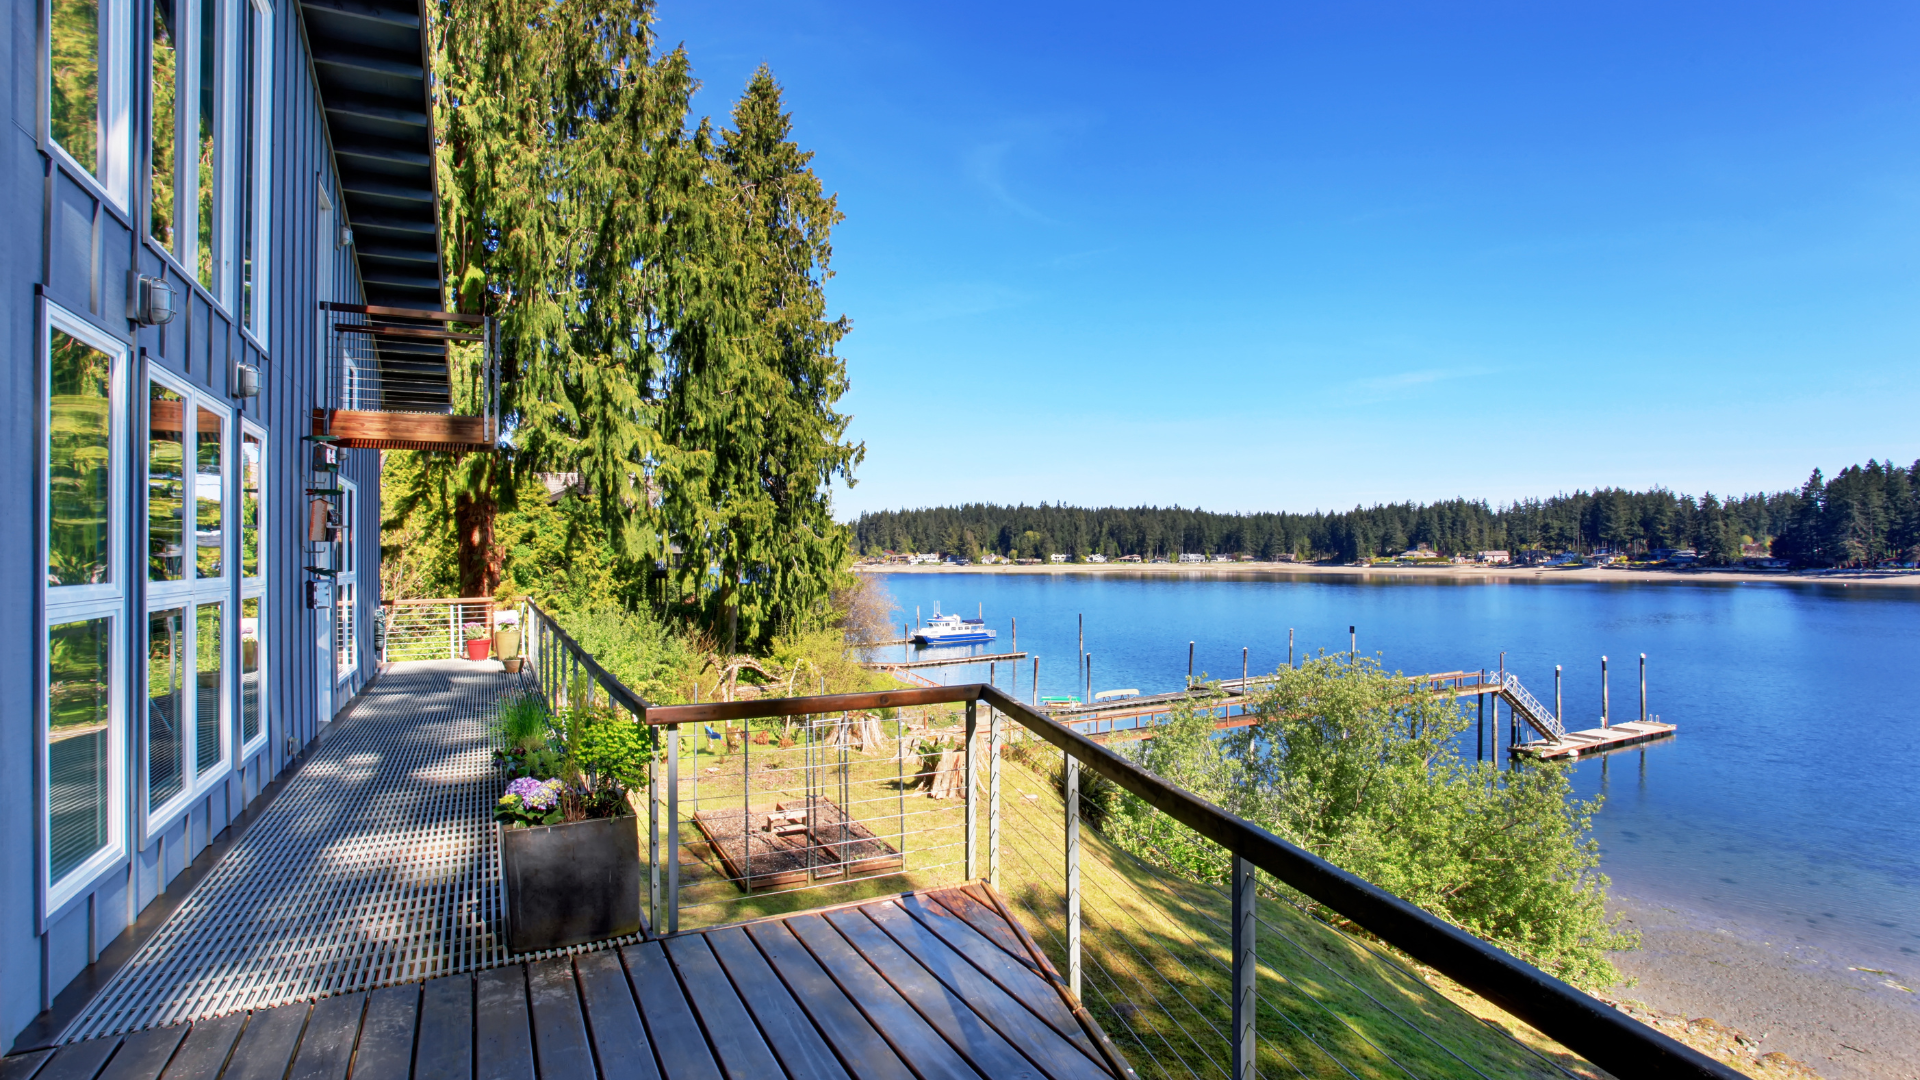
Owning a vacation home or an investment rental property is a dream for many Canadians. Whether it’s a cottage on the lake for family getaways or a rental unit to generate extra income, real estate can be both a lifestyle choice and a smart financial move. But before you dive in, it’s important to know what lenders look for when financing these types of properties. 1. Down Payment Requirements The biggest difference between buying a primary residence and a vacation or rental property is the down payment. Vacation property (owner-occupied, seasonal, or secondary home): Typically requires at least 5–10% down, depending on the lender and whether the property is winterized and accessible year-round. Rental property: Usually requires a minimum of 20% down. This is because rental income can fluctuate, and lenders want extra security before approving financing. 2. Property Type & Location Not all properties qualify for traditional mortgage financing. Lenders consider: Accessibility : Is the property accessible year-round (roads maintained, utilities available)? Condition : Seasonal or non-winterized cottages may not meet standard lending criteria. Zoning & Use : If it’s a rental, lenders want to ensure it complies with municipal bylaws and zoning regulations. Properties that fall outside these norms may require financing through alternative lenders, often with higher rates but more flexibility. 3. Rental Income Considerations If you’re buying a property with the intent to rent it out, lenders may factor the rental income into your mortgage application. Long-term rentals : Lenders typically accept 50–80% of the expected rental income when calculating your debt-service ratios. Short-term rentals (Airbnb, VRBO, etc.) : Many traditional lenders are cautious about using projected income from short-term rentals. Alternative lenders may be more flexible, depending on the property’s location and your financial profile. 4. Debt-Service Ratios Lenders use your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios to determine if you can handle the mortgage payments alongside your other obligations. With investment or vacation properties, lenders may apply stricter guidelines, especially if your primary residence already carries a large mortgage. 5. Credit & Financial Stability Your credit score, employment history, and overall financial health still matter. Since vacation and rental properties are considered higher risk, lenders want reassurance that you can handle the additional debt—even if rental income fluctuates or the property sits vacant. 6. Insurance Requirements Rental properties often require specialized landlord insurance, and vacation homes may need coverage tailored to seasonal or secondary use. Lenders will want proof of adequate insurance before releasing mortgage funds. The Bottom Line Buying a vacation property or rental can be exciting, but financing these purchases comes with extra rules and considerations. From higher down payments to stricter property requirements, lenders want to be confident that you can handle the responsibility. If you’re considering a second property, the best step is to work with a mortgage professional who can compare lender requirements, outline your options, and find the financing that works best for you. Thinking about making your dream of a vacation or rental property a reality? Connect with us today.
By Kambi Heywood • October 29, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.
By Kambi Heywood • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
Show More

Frequently Asked Questions

  • What does a mortgage broker do?

    When you go to your bank, you're getting one lender's products — take it or leave it. When you work with me, I shop your mortgage across dozens of lenders to find the right fit for your situation. I work for you, not the bank. That means more options, honest advice, and usually no cost to you — my fee is paid by the lender when your mortgage closes.

  • Who do you help? Are you only for first-time buyers?

    Not at all. I work with Canadians at every stage of the homeownership journey — first-time buyers, people purchasing their next home, self-employed borrowers, newcomers to Canada, seniors exploring reverse mortgages, investors, and anyone going through a divorce or separation. If a mortgage is involved, I can help.

  • Do you charge fees?

    In most cases, no. My services are typically provided at no cost to you — the lender pays my fee when your mortgage is arranged. For more complex situations, like private lending or certain alternative financing scenarios, I'll always be upfront about any costs before we proceed. No surprises — that's my commitment.

  • Are you licensed to help with properties in Alberta, or only BC?

    Both. I'm dual-licensed in BC and Alberta, which means I can help clients with properties on either side of the Rockies. Whether you're buying in Cranbrook, Fernie, or across the border in Alberta, I've got you covered.

  • How do I know what mortgage I can actually afford?

    The best place to start is a quick conversation. I'll look at your income, debts, down payment, and goals to give you a clear, realistic number — not just a ballpark. You can also try my affordability calculator on this page for a 30-second snapshot. But numbers without context only tell part of the story. Let's talk.

  • How long does it take to get a mortgage approved?

    It varies, but I work to make the process as efficient as possible. Once I have your documents and application, pre-approvals can often be issued within 24–48 hours. Full approval timelines depend on the lender and complexity of your file. I'll keep you informed every step of the way — you'll always know exactly where things stand.

  • I'm self-employed. Can I still qualify for a mortgage?

    Yes. Self-employed borrowers absolutely can qualify — it just requires a lender who understands how your income is structured. I work with lenders who have strong self-employed programs and know how to properly assess income that doesn't come from a T4. Let's look at your full picture together.

  • What if I have less-than-perfect credit?

    Credit challenges don't automatically disqualify you from getting a mortgage — they just change the approach. Depending on your situation, there may be options available through alternative lenders or a structured plan to strengthen your credit before applying. I'll give you an honest assessment and a clear path forward, whatever that looks like.

  • I'm going through a divorce. Can you help me sort out the mortgage on our shared home?

    Yes, and I understand this is one of the most stressful situations a person can navigate. Whether you're looking to buy out your spouse, refinance to remove a name from title, or figure out what you can qualify for on your own, I can help you work through the options clearly and without judgment.

  • What areas do you serve?

    I'm based in Cranbrook, BC, and serve clients throughout the East Kootenays, the broader BC Interior, and Alberta. Thanks to my dual license, geography isn't a barrier — and most of our process can be handled remotely, so wherever you are, we can work together.
Still have a question?

CONTACT